2026-10-15 · 5 min read · Collin County
Why Does Homeowners Insurance Matter Before You Buy in Frisco, Texas?
Why does homeowners insurance matter before you buy in Frisco, Texas?
Homeowners insurance matters before you buy in Frisco, Texas because the quote, and the deductible inside it, is a real part of your monthly cost, not a footnote at the end of the process. North Texas storms bring hail and wind, and insurers have been adjusting what they charge and what they cover. The short answer is also in my FAQ.
I'm Omega Mejia, a real estate agent serving Frisco and Collin County, and I wrote this for a buyer getting ready to make an offer. I am not an insurance agent, and I will not tell you which policy to buy. I will tell you which questions buyers wish they had asked before the offer, because I have watched a good house become a stressful one over a number nobody checked. Nothing about the house had changed. The only surprise was the date on the roof and what the policy said about it.
What is the number most buyers never see coming?
It is the deductible, and the form it takes. The Texas Department of Insurance explains that a deductible can be a flat dollar amount or a percentage, and it tells consumers to convert a percentage into dollars before they buy. Its own example is worth remembering: on a home insured for $150,000, a 5 percent deductible is $7,500. In the same example, a hail storm damages a roof, and the policy with the $500 deductible pays while the policy with the 5 percent deductible pays nothing, because the repair costs less than the deductible.
Read that twice. Two homeowners can have the same storm and the same damage and walk away with opposite results. A buyer who only compares the premium compares the wrong number. I want the wind and hail deductible in dollars for the specific house before we write the offer.
Why does the roof change the conversation?
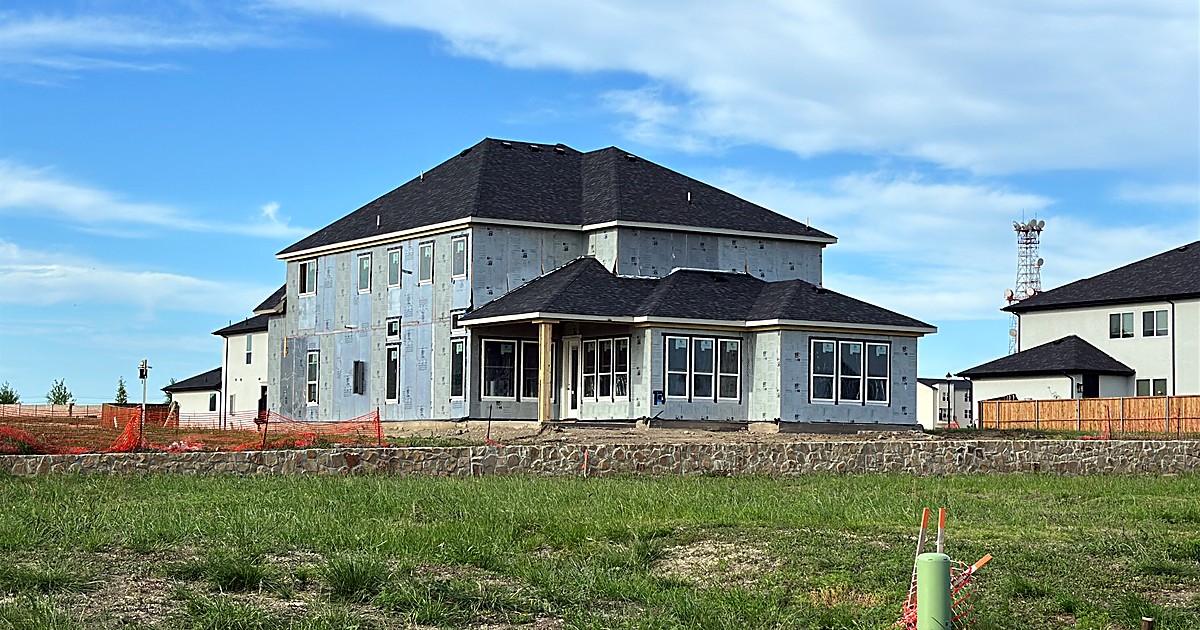
In hail country the roof is the first thing everyone talks about, and for good reason. Roof age, material and condition can affect whether a company will write a policy and how it prices one. The Texas Department of Insurance also notes that an impact-resistant roof may qualify for a discount with some companies.
So when I tour a home with a buyer, I look at the roof the way an insurance underwriter might: How old does it appear? Are there patches, missing granules, or sagging? Then I note it for the inspection and for the insurance call. The home inspection covers condition. The insurance company decides what it will do about it. Those are two separate conversations, and you want both answers while you still have time to act on them. Buyers who wait until the week of closing have fewer options and more stress, and I would rather you have a calm month than a rushed day.
What does replacement cost versus actual cash value mean?
The Texas Department of Insurance describes it this way. Replacement cost pays to repair or replace at current prices. Actual cash value pays that amount minus depreciation for age and wear. On an older roof, the gap can be large. TDI advises making sure your policy has replacement cost coverage to be fully protected, and its roof example shows how much more you could pay out of pocket under actual cash value.
Some policies treat roofs differently from the rest of the house, so the basis that applies to the roof is the line that matters most in a quote. That answer sits in the written policy, not in anyone's memory of a phone call.
When should you get a homeowners insurance quote?
Before you are committed. A Texas contract includes an option period that gives you time to decide, and I walk clients through how that works in my guide to inspections and the option period. The quote on the specific address belongs early in that window, along with the property details and the roof notes from our tour.
Insurers may also look at a home's claims history. TDI explains that companies can check a report covering the last seven years, so I find out what the seller knows about past claims while you still have time to act. Surprises at this stage are cheaper than surprises after closing.
What if a company will not renew a policy?
It happens, and the Texas Department of Insurance has a page on your rights. If you ask, a company must explain in writing why it did not renew, and a homeowner can file a written complaint with the department if they believe a company acted improperly. Notice periods differ depending on when the policy was bought or renewed.
My practical advice is not insurance advice, only a habit. Keep your maintenance records, take dated photos after repairs, and keep your policy documents in one folder. Those habits also help you at resale. A buyer likes a home with a paper trail.
How does the insurance quote fit into your offer on a Frisco home?
It sits beside the tax estimate and the lender's numbers, so you know what a home costs per month before you decide. My making an offer page and buying a home guide show where it fits. If you are building, my new construction page covers the questions I ask builders.
If you want to compare a few homes in Frisco, McKinney or Allen with the insurance questions in mind, contact me.
This is general information about my approach, not legal, tax, financial or insurance advice. Deductible and coverage examples come from the Texas Department of Insurance, and a licensed insurance agent provides the quote on your address.
Frequently asked questions
- Why does homeowners insurance matter before you buy in Frisco, Texas?
- North Texas storms bring hail and wind, and insurers have adjusted pricing and coverage. The quote on the specific address affects the monthly cost of the home.
- What is a percentage deductible?
- Per the Texas Department of Insurance, a deductible can be a set dollar amount or a percentage of the insured value. On a $150,000 insured home, a 5 percent deductible equals $7,500.
- What is the difference between replacement cost and actual cash value?
- Replacement cost pays to repair or replace at current prices. Actual cash value subtracts depreciation, so on an older roof the gap can be large.
- When should I get an insurance quote?
- Before you are committed. The quote on the specific address belongs early in the option period, with the roof's age and condition in front of the insurance agent.
- Can you recommend an insurance policy?
- No. I am a real estate agent, not an insurance agent. I can tell you which questions matter, and a licensed insurance agent gives you the real numbers.